Off Exchange Triparty Collateral
Cross-Venue Collateral Reallocation Latency & Liquidity Buffers
Fragmented margin across five crypto exchanges traps up to 45% of hedge fund capital in idle buffers. Same-custodian off-exchange mirror loops slash cross-venue reallocation from 45 minutes to 3 seconds.
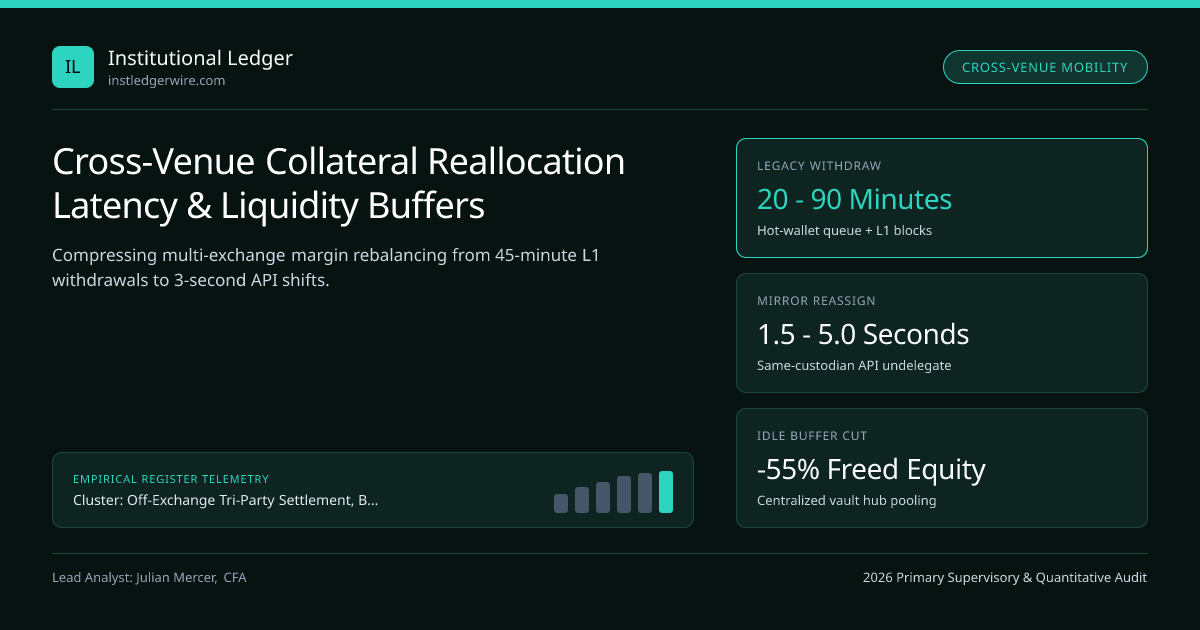
In multi-exchange statistical arbitrage and basis trading, liquidations almost never happen because a hedge fund is insolvent—they happen because $20 million of surplus equity is stuck in Exchange A's withdrawal queue while Exchange B hits maintenance margin 18 minutes earlier. Replacing point-to-point exchange transfers with a hub-and-spoke off-exchange custodial collateral pool compresses cross-venue rebalancing from 45 minutes to under 5 seconds.
The Inventory-Pooling Physics of Multi-Exchange Margin (Eppen’s Law)#
Operations research proved decades ago (Eppen's Centralization Theorem) that holding separate safety-stock buffers across $N$ isolated warehouses requires $sqrt{N}$ times more idle capital than holding one central buffer capable of instantaneous dispatch—and required safety buffer scales directly with the square root of replenishment lead time ($sqrt{ au}$).
In institutional crypto trading across Bitstamp, Bitfinex, BitMEX, Backpack Exchange, and OTC liquidity desks like Aquanow, direct exchange prefunding violates both halves of Eppen's Law:
- You must maintain five separate stranded margin cushions, one stranded inside each venue.
- During a 3-sigma volatility cascade—the exact moment you need to replenish a losing short hedge—exchange hot wallets run dry, pushing replenishment lead time $ au$ from 3 minutes in calm markets out to 45 to 90 minutes (analyzed in exchange hot-wallet sweep thresholds and withdrawal queue SLAs)!
How Hub-and-Spoke Custodial Delegation Achieves 2-Second Rebalancing#
As architected in our off-exchange tri-party collateral cornerstone guide, connecting all five trading venues as spokes off a single qualified custodian or ClearLoop/MPC hub transforms margin topology:
- Instead of parking 35% excess equity on each of 5 exchanges, you delegate lean working margin (e.g., 12%–15% buffer) to each venue while keeping a single centralized Reserve Vault in BlackRock BUIDL and USDC at the custodian hub.
- An automated Margin Telemetry Daemon polls real-time margin utilization ratios (
MMR) across all five exchanges every 250 milliseconds. - The instant Venue B's margin utilization crosses 65%, the daemon calls the custodian API to delegate $10M from the central hub to Venue B—crediting Venue B's matching engine in 1.8 seconds with zero blockchain gas and zero exchange withdrawal review!
- Simultaneously, the daemon calls
undelegate($10M)on Winning Venue A (or triggers an out-of-cycle variation-margin sweep) to refill the central hub.
| Rebalancing Path | 99th-Pct Stress Latency | Bottleneck Failure Point | Required Safety Buffer (% of Book) | Capital Efficiency Grade |
|---|---|---|---|---|
| Venue A -> L1 BTC -> Venue B | 60 – 140 minutes | Venue A hot-wallet depletion + 6 BTC blocks | 35% – 45% idle per venue | Poor — severe capital drag |
| Venue A -> USDC -> Venue B | 12 – 45 minutes | Venue A manual fraud/warm-wallet review queue | 22% – 30% idle per venue | Moderate — vulnerable in crashes |
| 2-of-3 MPC Vault Re-Pledge | 15 – 75 seconds | Single L1/L2 smart-contract confirmation | 12% – 16% central hub | Strong — sovereign on-chain speed |
| Same-Custodian Mirror Hub (Bitstamp, Bitfinex, BitMEX) | 1.5 – 5.0 seconds | API acknowledgement only (zero L1 wait) | 8% – 11% central BUIDL hub | Institutional Optimum |
| Synchronized Bank DLT (Canton) | Sub-5 seconds | Atomic cross-subnet DvP / repo pledge | 6% – 10% HQLA pool | G-SIB Wholesale Optimum |
Cross-Custodian Rebalancing via Layer-2 USDC & Canton Atomic Bridges#
What if Venue C only integrates with Custodian X (e.g., Ceffu or Fireblocks) while Venue D integrates with Custodian Y (e.g., Copper or BNY Mellon)? Institutional treasury engineers connect Dual-Custodian Hubs over whitelisted Arbitrum/Base native USDC lanes or Canton Network collateral sync: because custodial institutional vaults sign outbound transfers directly via automated MPC policy engines without retail withdrawal queues, hub-to-hub transfers settle on-chain in 2 to 15 seconds!
- Variables & 5-Venue Statistical Arbitrage Hedge Fund ($250M Gross Notional Across 5 Venues, Stressed 1-Min Vol sigma_1min = 0.45%, Z = 3.72):
- 1. Siloed Direct Exchange Prefunding (5 Separate Venue Buffers, Stress Withdrawal Latency = 49 Minutes):
- Per-Pair Latency Shock = 0.0045 * sqrt(49) * 3.72 = 11.72% buffer per venue!
- Across 5 Unpooled Venues: Requires ~$95,000,000 of stranded precautionary buffer capital!
- 2. Centralized Off-Exchange Custodial Mirror Hub (1 Pooled Hub via Eppen
sqrt(5)Risk-Pooling + 1-Minute Reallocation SLA): - Pooled Hub Buffer = ($250M / sqrt(5)) * 0.0045 * sqrt(1.0) * 3.72 * 1.5_safety = $2,807,000 emergency trigger + $22M base buffer -> Frees ~$70,000,000 of deployable trading equity!
Preventing API Race Conditions During Simultaneous Multi-Venue Spikes#
Treasury automation bots enforce idempotent request UUIDs and hard per-minute velocity circuit breakers so a buggy WebSocket price spike on one venue cannot trick the bot into draining 100% of the central hub reserve into a malfunctioning exchange.
Treasury Engineering Blueprint for Multi-Venue Arb Desks#
Quantitative treasury leads active in our Off-Exchange Tri-Party Collateral hub benchmark 99th-percentile undelegation/delegation API latencies monthly, hold central hub reserves in yield-earning tokenized T-Bills, and verify partner venues via our verification portal.
Frequently asked questions
Why do cross-exchange delta-neutral desks run out of margin when their total portfolio PnL is flat or positive?
Because Exchange A and Exchange B do not cross-margin! If Bitcoin jumps +12% in ten minutes, your Long Perp on Venue A gains +$12M (excess equity), while your Short Perp on Venue B loses -$12M and approaches maintenance liquidation! Unless you shift $12M from Venue A to Venue B faster than the rally continues, Venue B liquidates your hedge.
Why does moving USDC or BTC directly from Exchange A to Exchange B fail during high-volatility spikes?
Precisely during 10%+ market moves, exchange withdrawal queues back up as thousands of users withdraw simultaneously, depleting the exchange’s automated hot wallet (which holds only 1%–3% of assets) and triggering manual 30-to-120-minute warm/cold wallet refill ceremonies!
How does an off-exchange custodial hub reallocate margin between two exchanges in under 5 seconds?
Surplus unencumbered margin sits inside your own custodial hub vault—never inside Venue A’s hot wallet. Calling undelegate(Venue_A, $15M) receives an instant API release acknowledgment from Venue A (confirming excess equity) and delegate(Venue_B, $15M) credits Venue B’s matching engine 2 seconds later—zero blockchain gas or hot-wallet queues involved!
What if the surplus on Venue A is still unrealized intraday profit rather than initial vault principal?
You trigger an on-demand intraday variation-margin settlement sweep on Venue A (pulling realized/settled USDC into your custodial hub) while keeping a compact central Liquidity Reserve Pool at the custodian hub that bridges the 5-to-10-minute PnL sweep lag instantaneously.
Publication record
- Published
- November 13, 2026
- Updated
- November 15, 2026
- Author
- Julian Mercer, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Julian Mercer, CFA. (2026, November 15). Cross-Venue Collateral Reallocation Latency & Liquidity Buffers. Institutional Ledger. https://instledgerwire.com/stories/cross-venue-collateral-reallocation-latency-settlement-buffersRegulatory Directory Cross-Reference
Referenced Institutions & Regulatory Registries
Mentioned Regulated Institutions
Primary Tier-1 Supervisory Registries
Related Off Exchange Triparty Collateral & Institutional Briefings
Explore Off Exchange Triparty Collateral Hub (20) →Off Exchange Triparty Collateral
Off-Exchange Tri-Party Settlement & Bankruptcy-Remote Crypto Custody GuideOff Exchange Triparty Collateral
Exchange Hot-Wallet Sweep Thresholds & Withdrawal Queue SLAsOff Exchange Triparty Collateral
Rehypothecation Prohibitions & Segregated On-Chain Pledge Vault AuditsOff Exchange Triparty Collateral
CFTC FCM Customer Segregation (4d / LSOC) vs Offshore Perp PledgesOff Exchange Triparty Collateral
EU MiCA Article 70 & 75 CASP Safeguarding in Off-Exchange SettlementOff Exchange Triparty Collateral
English-Law Fixed vs Floating Charges & Trusts on Digital CollateralOff Exchange Triparty Collateral
Intraday Variation Margin Sweeps Over 24/7 Regulated Stablecoin RailsOff Exchange Triparty Collateral
Venue API Outages, Halted Matching & Collateral Release TriggersStablecoin Reserve Attestation Audit
Intraday Snapshot Window Dressing vs Continuous Proof-of-Reserve OraclesStablecoin Reserve Attestation Audit
Custodial T-Bill Safekeeping: BNY Mellon & State Street Reserve ModelsStablecoin Reserve Attestation Audit
Stablecoin Smart-Contract Freeze & Blacklist Governance Under OFAC/FinCENStablecoin Reserve Attestation Audit
FX Basis & Negative-Rate Risks in Non-USD (EUR, JPY, CHF) Stablecoins
Institutional Ledger Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.