Editorial Research Index
Institutional briefings & primary regulatory analysis
Financial analysis and briefings published by Institutional Ledger.
- Published briefings
- 231
- Thematic pillar hubs
- 25
20 matching briefings
Institutional Crypto Prime Brokerage, Cross-Venue Netting & zk-PoR Guide (2026)
Institutional crypto prime brokerage has rebuilt from the ground up since 2022—replacing opaque unsecured lending with bankruptcy-remote collateral netting, zk-SNARK Merkle-sum Proof-of-Reserves, and quantified staking risk models.
zk-SNARK Merkle-Sum Tree Proof-of-Reserves: Auditing Exchange Liabilities
Standard Merkle trees leak sibling balances or remain vulnerable to injected negative accounts. Combining Merkle-Sum Trees with Halo2/Plonky2 zk-SNARK circuits proves complete exchange solvency with zero privacy leakage.
Negative-Balance Non-Existence Proofs & Hidden Collateral Encumbrance Risk
Without strict 64-bit unsigned range proofs and off-chain encumbrance audits, a bankrupt exchange can inject a -$2B house account—or borrow tokens overnight—to spoof a 100% Proof-of-Reserves badge.
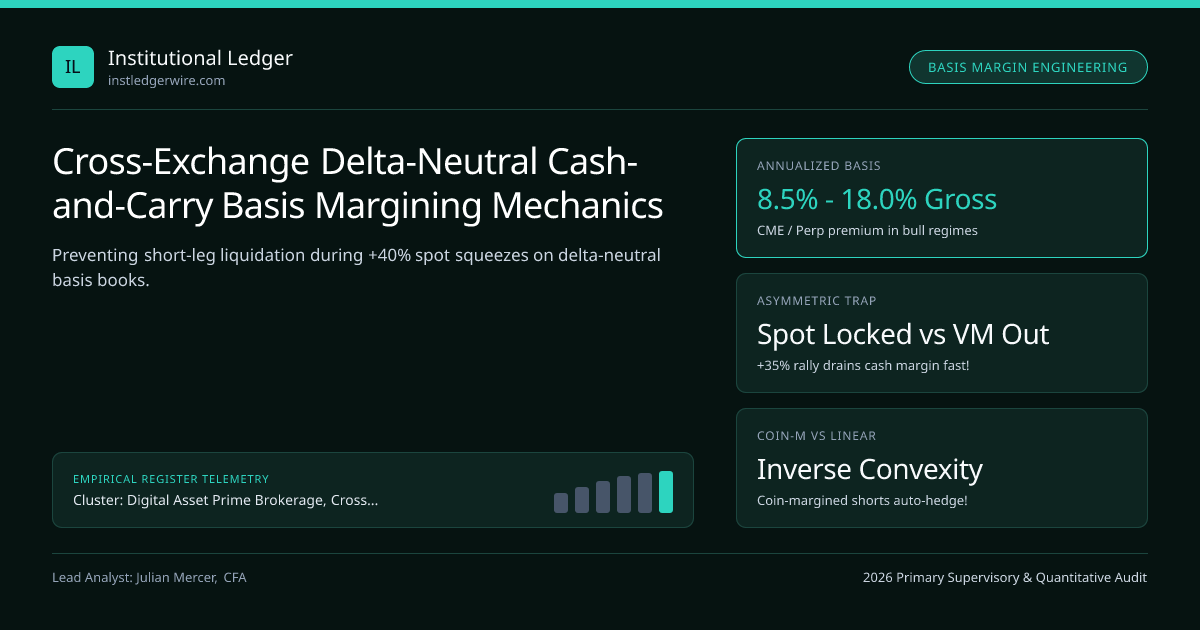
Cross-Exchange Delta-Neutral Cash-and-Carry Basis Margining Mechanics
A delta-neutral long-spot / short-futures crypto basis trade has zero terminal price exposure—yet asymmetric intraday variation-margin drains during parabolic rallies can liquidate under-buffered short legs!
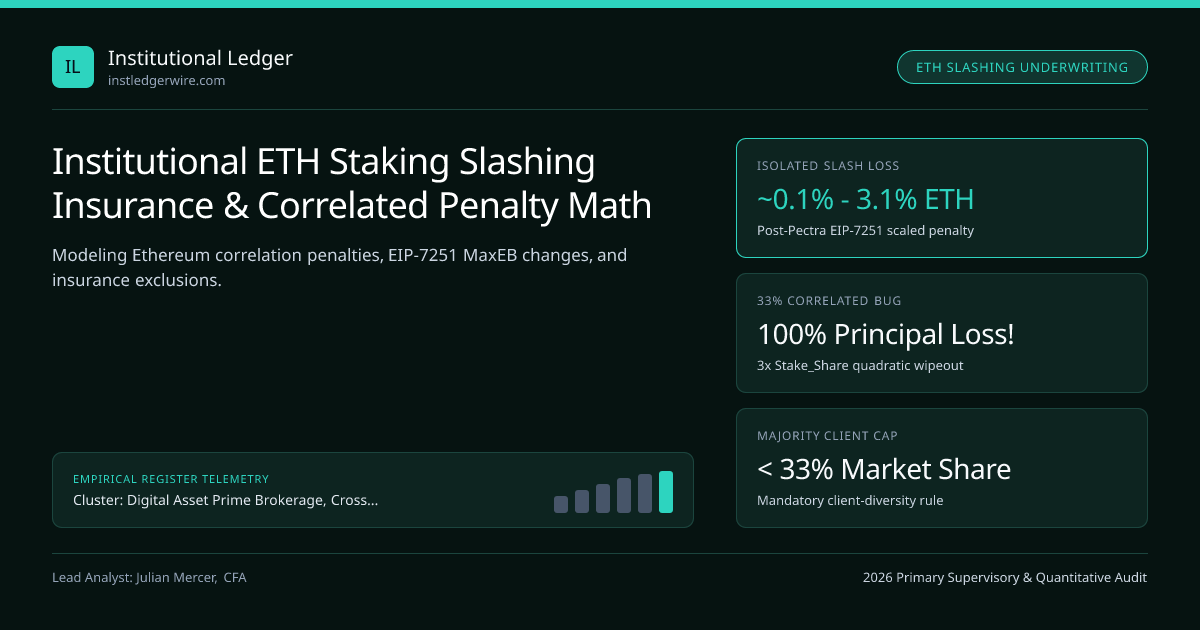
Institutional ETH Staking Slashing Insurance & Correlated Penalty Math
An isolated validator double-sign loses ~0.03 to 1 ETH, whereas a correlated client bug hitting 33% of Ethereum staked supply triggers a 100% principal wipeout—shaping every institutional slashing insurance policy!
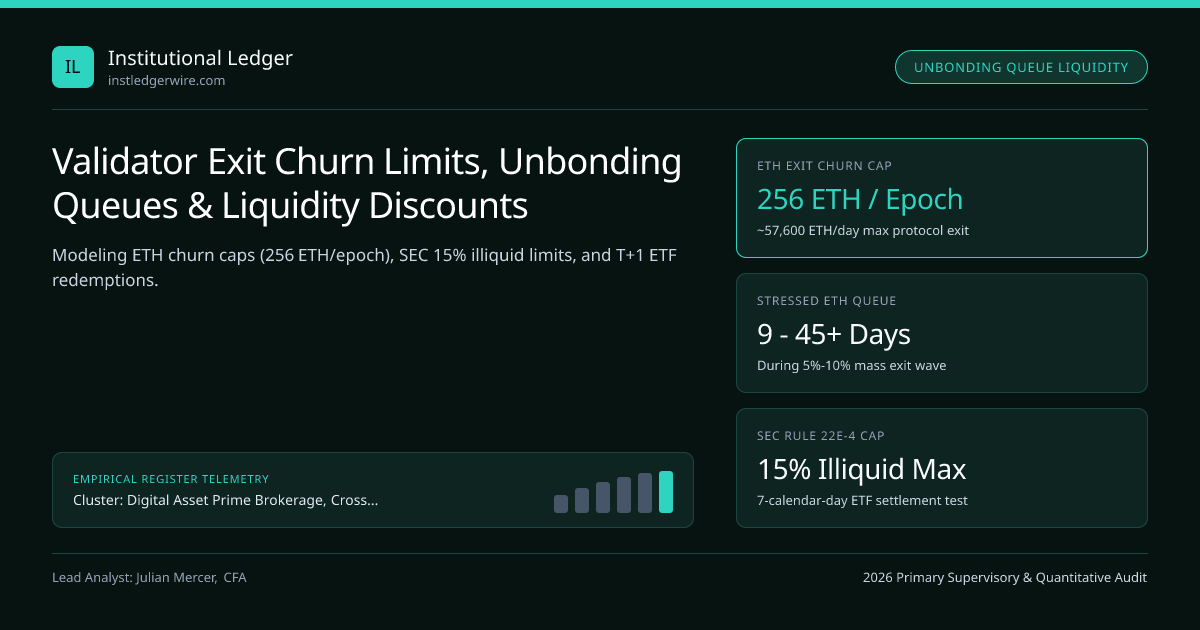
Validator Exit Churn Limits, Unbonding Queues & Liquidity Discounts
Native staked tokens cannot teleport back into liquid orderbooks during a crash: protocol exit-churn caps throttle Ethereum, Solana, and Cosmos unstake redemptions into multi-day or multi-week liquidity queues!
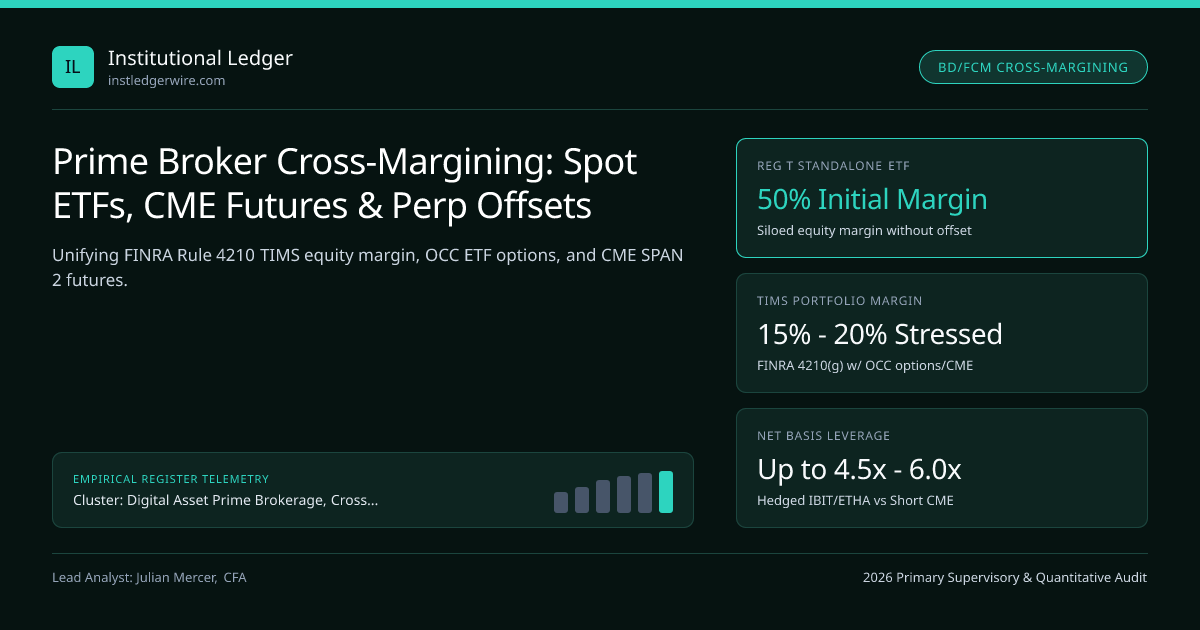
Prime Broker Cross-Margining: Spot ETFs, CME Futures & Perp Offsets
Dual-registered SEC Broker-Dealer and CFTC FCM prime brokers unlock up to 80% margin savings by recognizing delta and volatility offsets across Spot Crypto ETFs, OCC options, and CME futures.
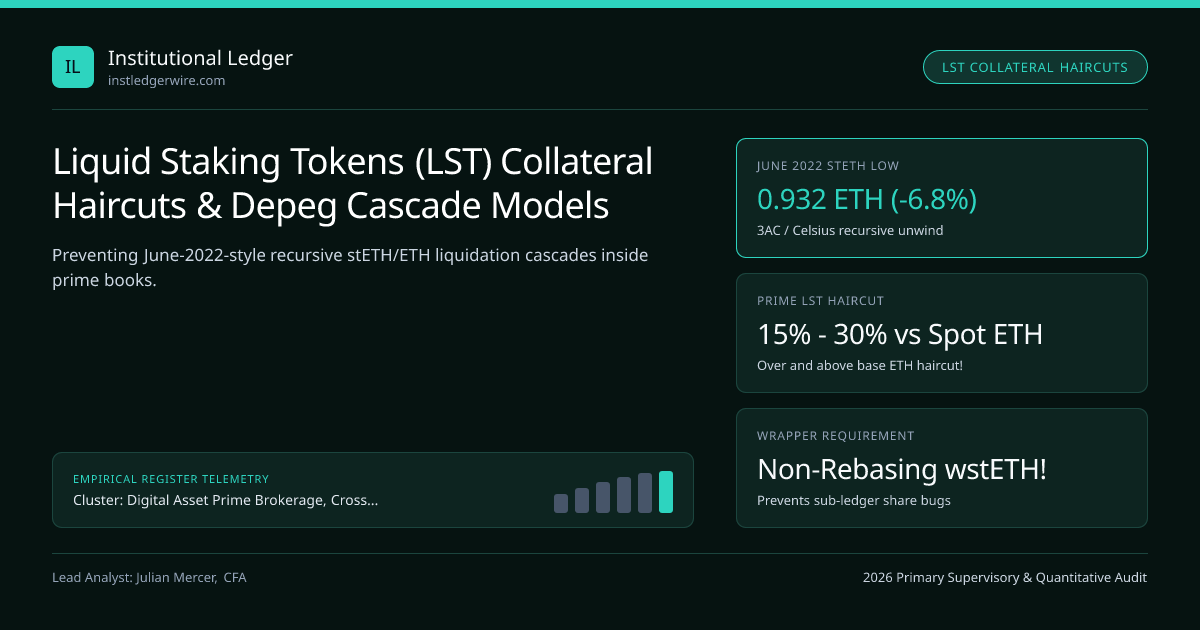
Liquid Staking Tokens (LST) Collateral Haircuts & Depeg Cascade Models
Posting wstETH or cbETH as margin collateral stacks staking yield atop derivatives execution—until a market panic exhausts DEX liquidity pools and triggers a secondary LST-to-ETH discount cascade!
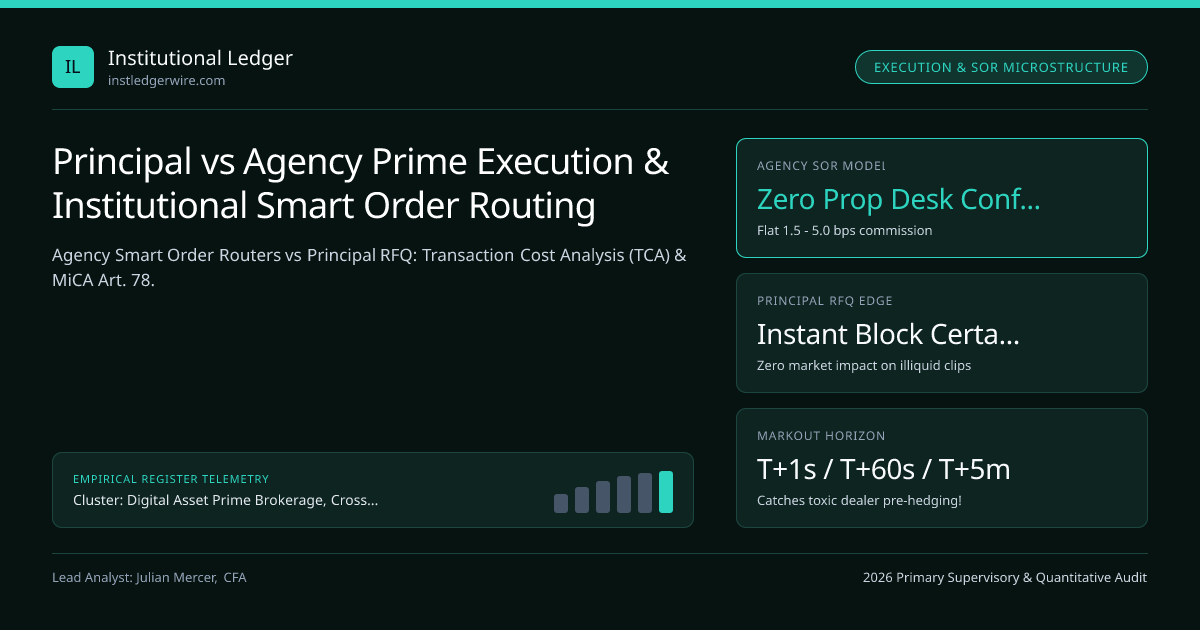
Principal vs Agency Prime Execution & Institutional Smart Order Routing
Routing a $50M institutional order through a conflicted principal desk leaks trading intent within milliseconds; understanding when to deploy agency TWAP/SOR algorithms versus multi-dealer blind RFQ saves 8 to 35 bps per trade!
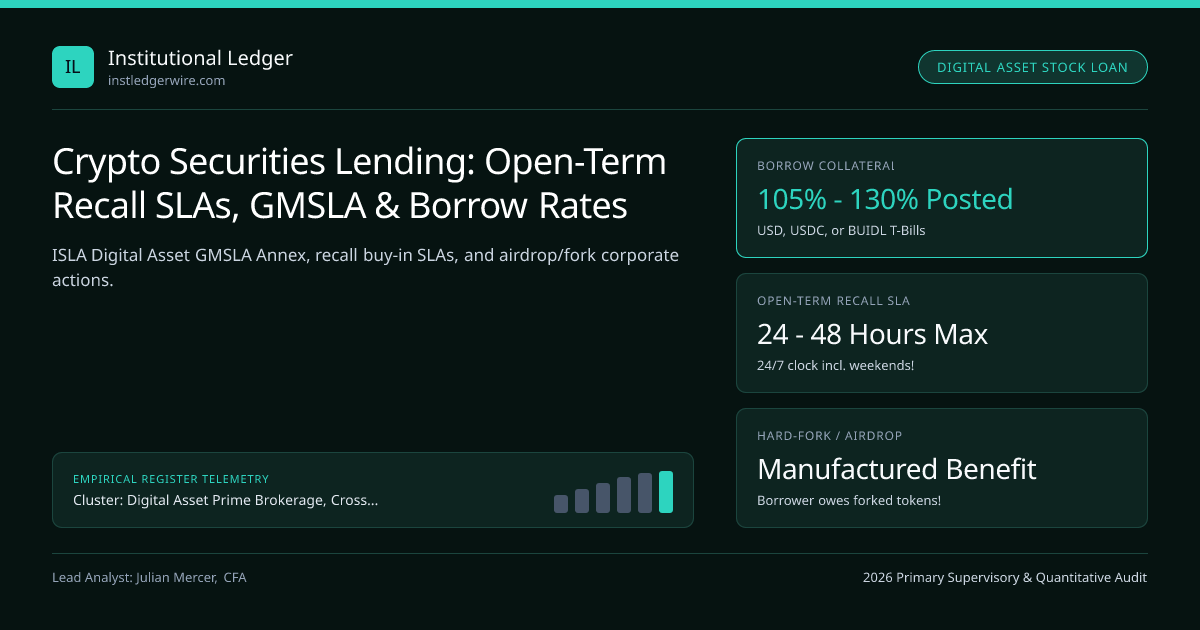
Crypto Securities Lending: Open-Term Recall SLAs, GMSLA & Borrow Rates
Shorting digital assets cleanly requires enforceable securities-lending agreements—governing 102%–125% cash/T-Bill collateralization, hard-to-borrow fee spikes, T+1 lender recall SLAs, and protocol hard-fork/airdrop corporate actions!
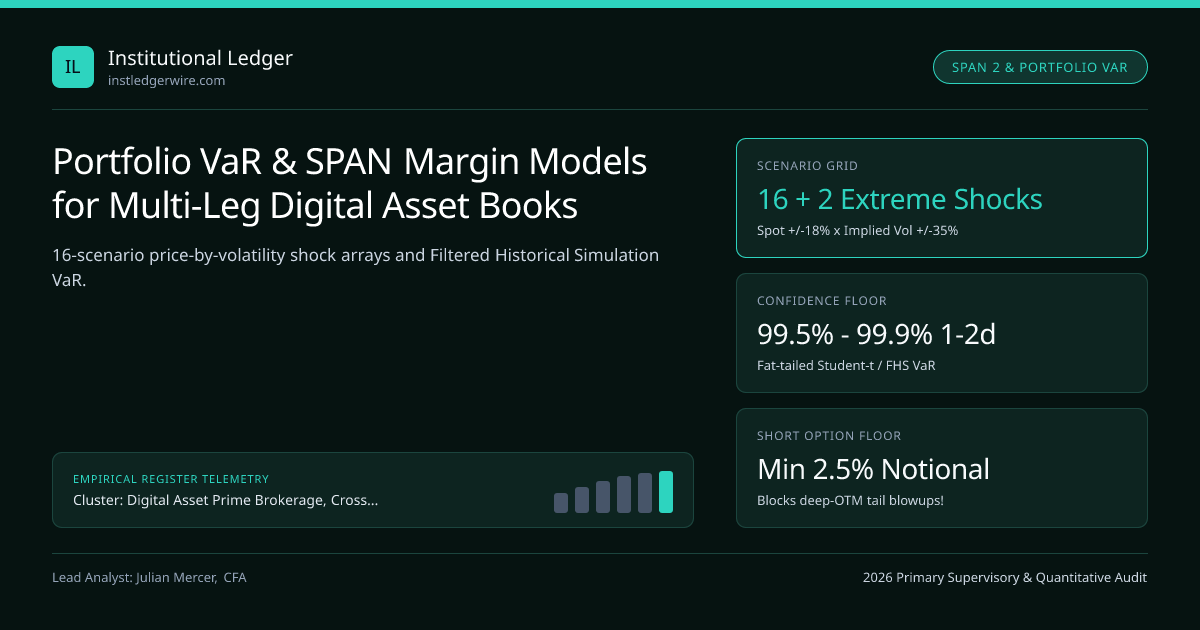
Portfolio VaR & SPAN Margin Models for Multi-Leg Digital Asset Books
Linear delta-sum margining penalizes hedged option butterflies, calendar spreads, and dispersion books; institutional prime engines deploy 16-point SPAN scenario grids and Filtered Historical Simulation VaR.
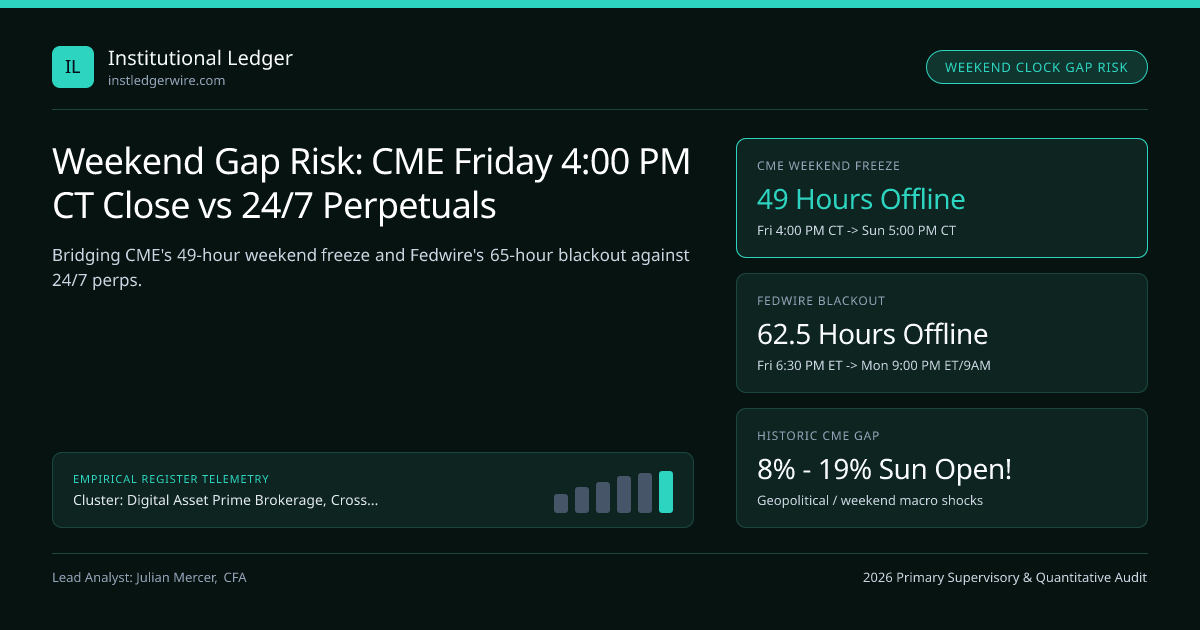
Weekend Gap Risk: CME Friday 4:00 PM CT Close vs 24/7 Perpetuals
Every Friday at 4:00 PM CT, CME crypto futures freeze for 49 hours while global spot and perpetuals trade nonstop—creating treacherous Sunday evening opening price gaps and trapped cash-margin waterfalls!
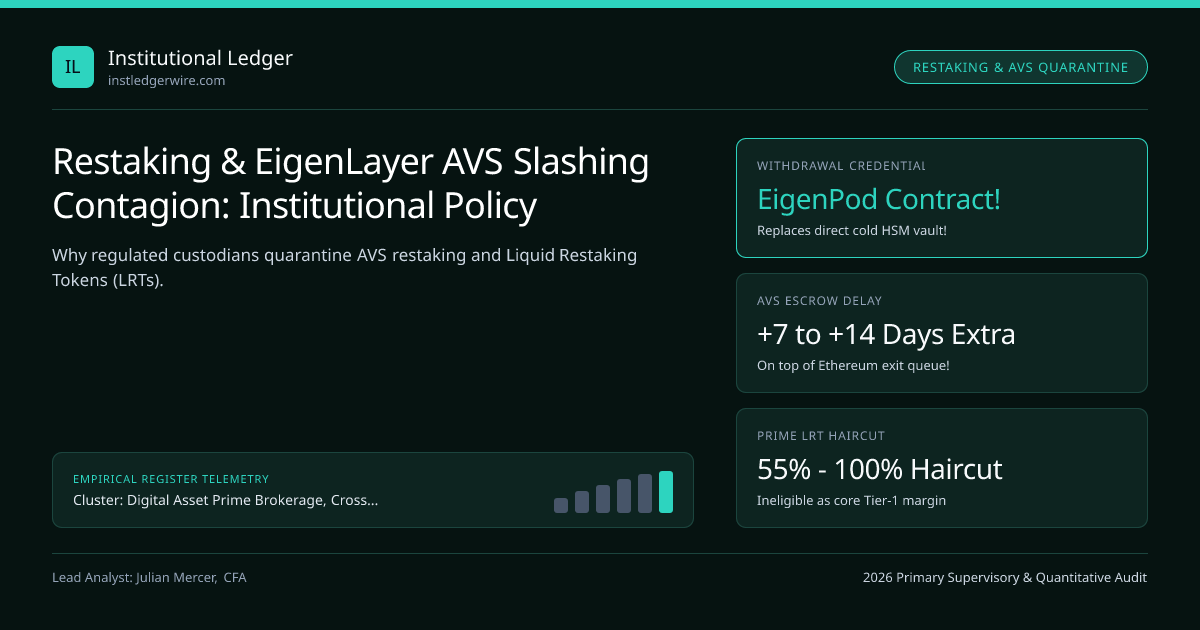
Restaking & EigenLayer AVS Slashing Contagion: Institutional Policy
Native Ethereum staking slashes solely on deterministic consensus equivocation; restaking exposes that same 32–2,048 ETH principal to custom Actively Validated Services (AVS) smart contracts, subjective faults, and escrow delays!
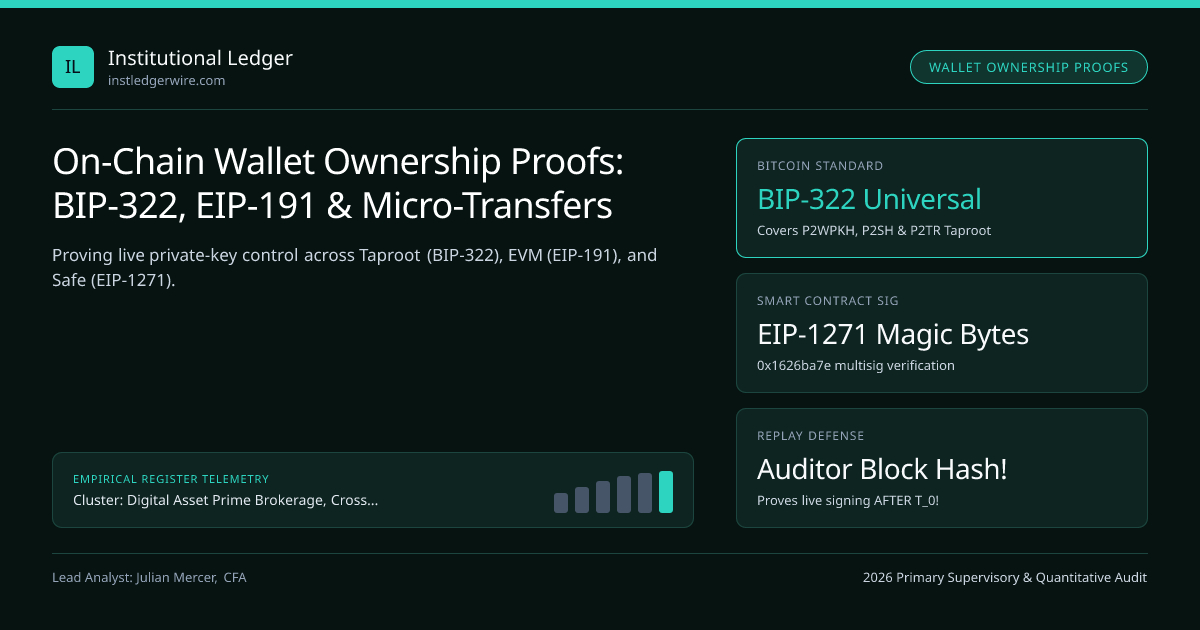
On-Chain Wallet Ownership Proofs: BIP-322, EIP-191 & Micro-Transfers
Anyone can paste a rich-list Bitcoin address into a spreadsheet; proving live uncompromised private-key control without waking air-gapped HSMs unnecessarily requires BIP-322, EIP-191, and EIP-1271 challenge protocols.
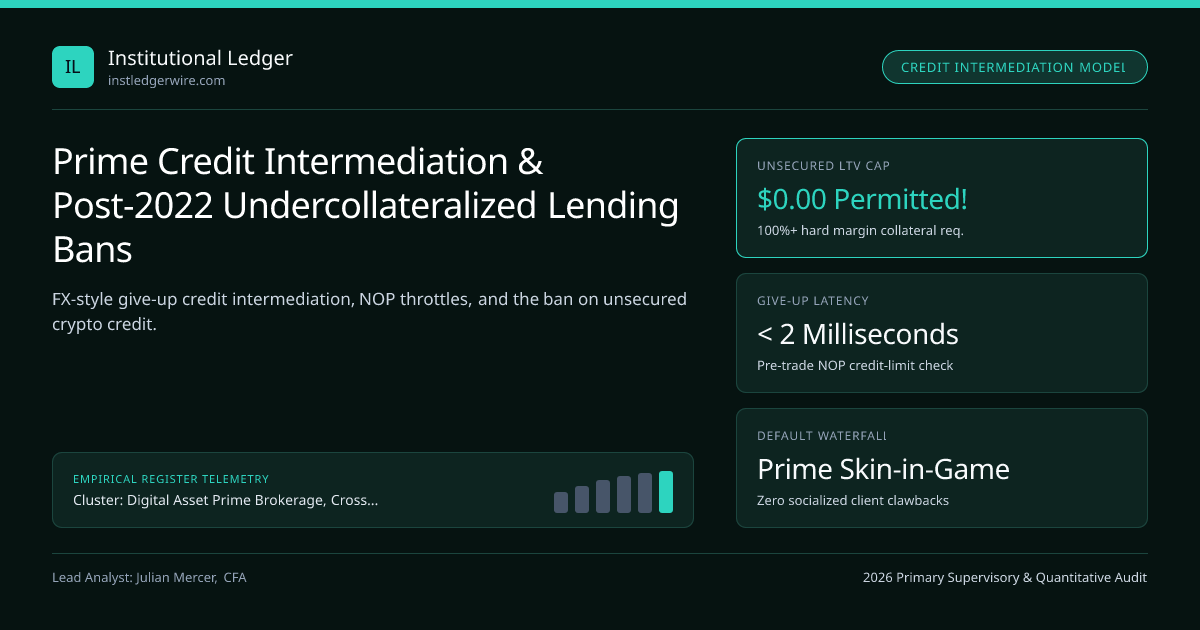
Prime Credit Intermediation & Post-2022 Undercollateralized Lending Bans
Three Arrows Capital borrowed billions from ten crypto lenders simultaneously using the same unverified NAV PDF; 2026 prime credit intermediation replaces blind balance-sheet loans with real-time Net Open Position caps!
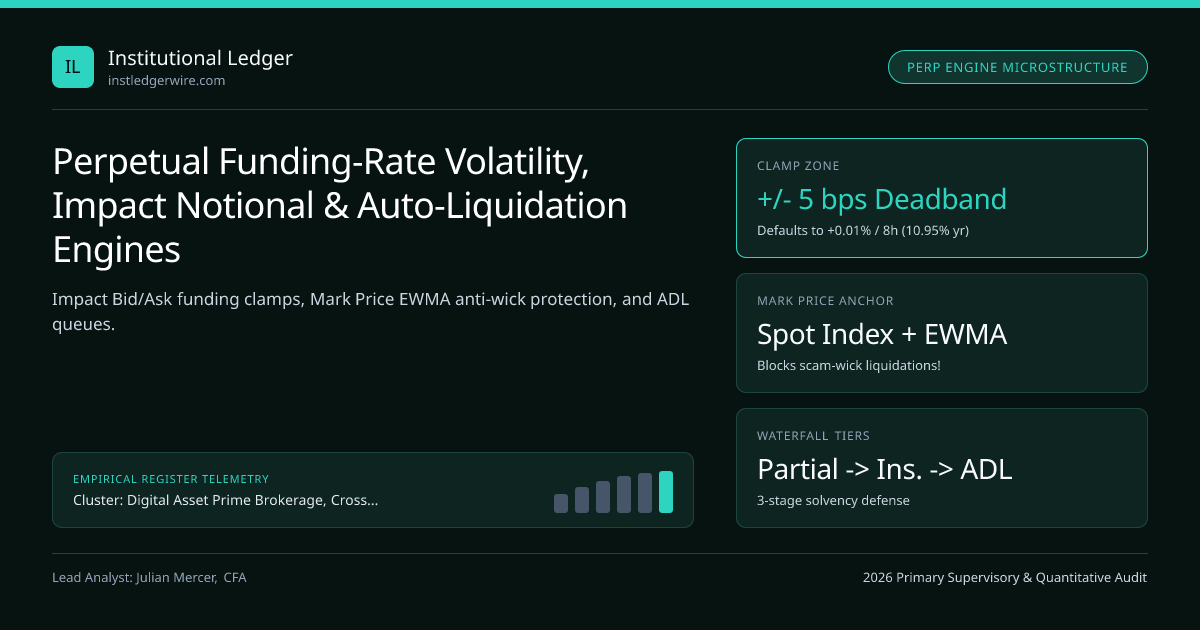
Perpetual Funding-Rate Volatility, Impact Notional & Auto-Liquidation Engines
Perpetual futures tether to spot without an expiry date via 1-to-8-hour funding transfers and Mark-Price auto-liquidation engines—mechanics every institutional quant must model down to the basis point!
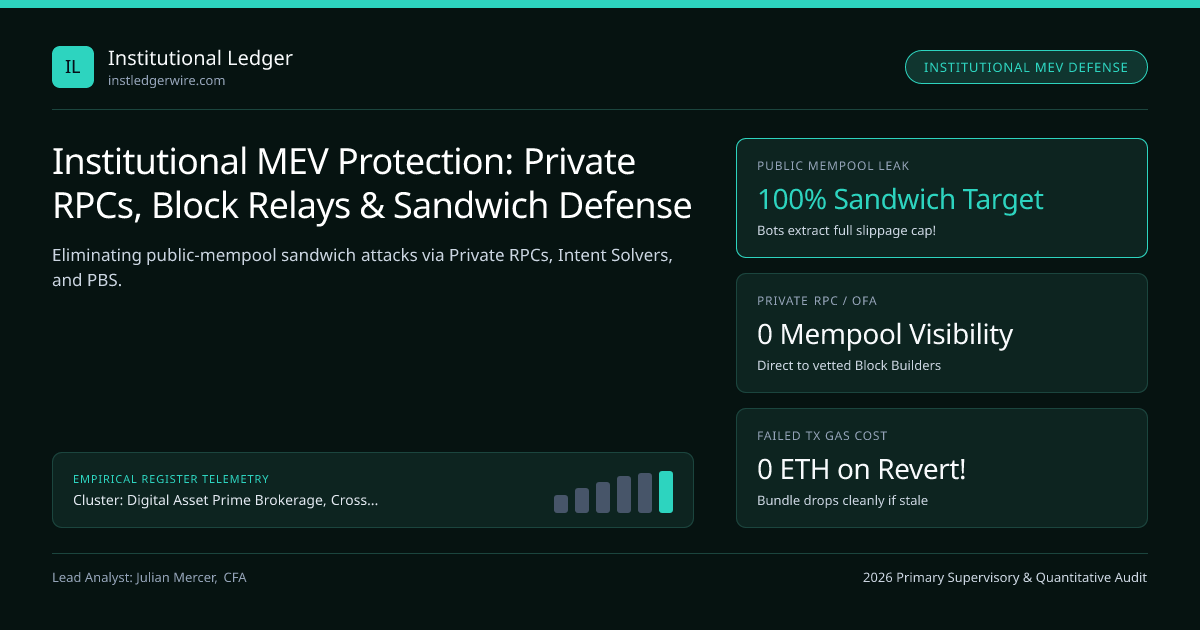
Institutional MEV Protection: Private RPCs, Block Relays & Sandwich Defense
Broadcasting a $10M on-chain swap with a naive 1.0% slippage tolerance to Ethereum’s public mempool guarantees an instant -$98,000 MEV sandwich extraction; private order-flow relays and solver auctions eliminate mempool leakage!
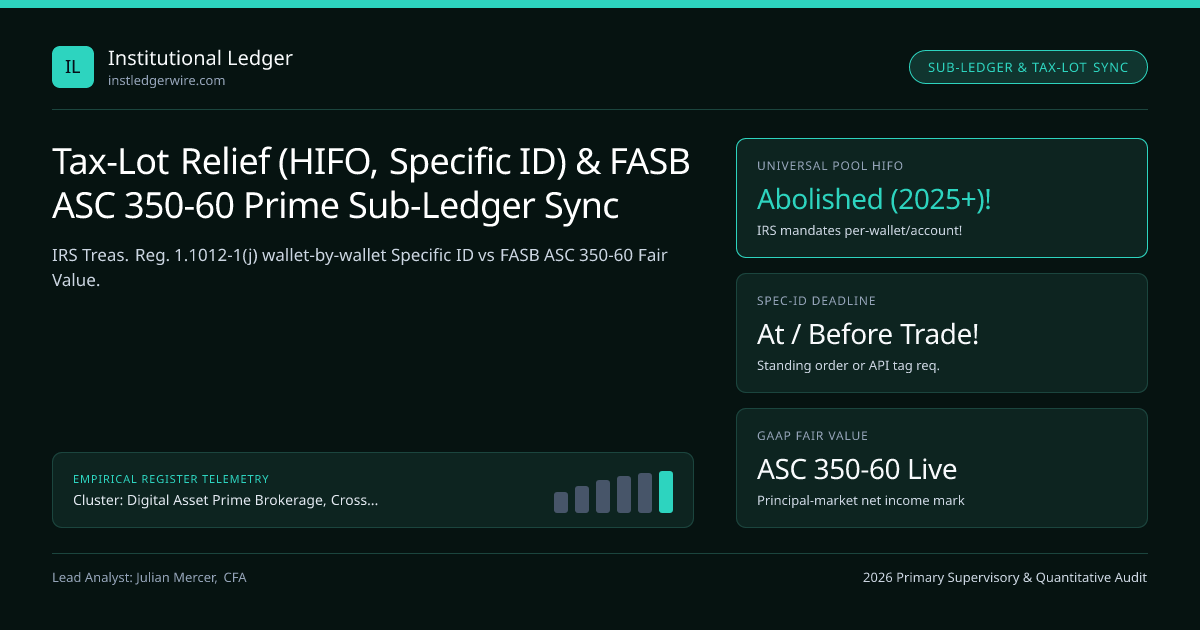
Tax-Lot Relief (HIFO, Specific ID) & FASB ASC 350-60 Prime Sub-Ledger Sync
Starting in 2025–2026, IRS broker rules mandate strict wallet-by-wallet pre-trade tax-lot identification—forbidding retroactive universal HIFO cherry-picking while GAAP books mark to fair value under FASB ASC 350-60!
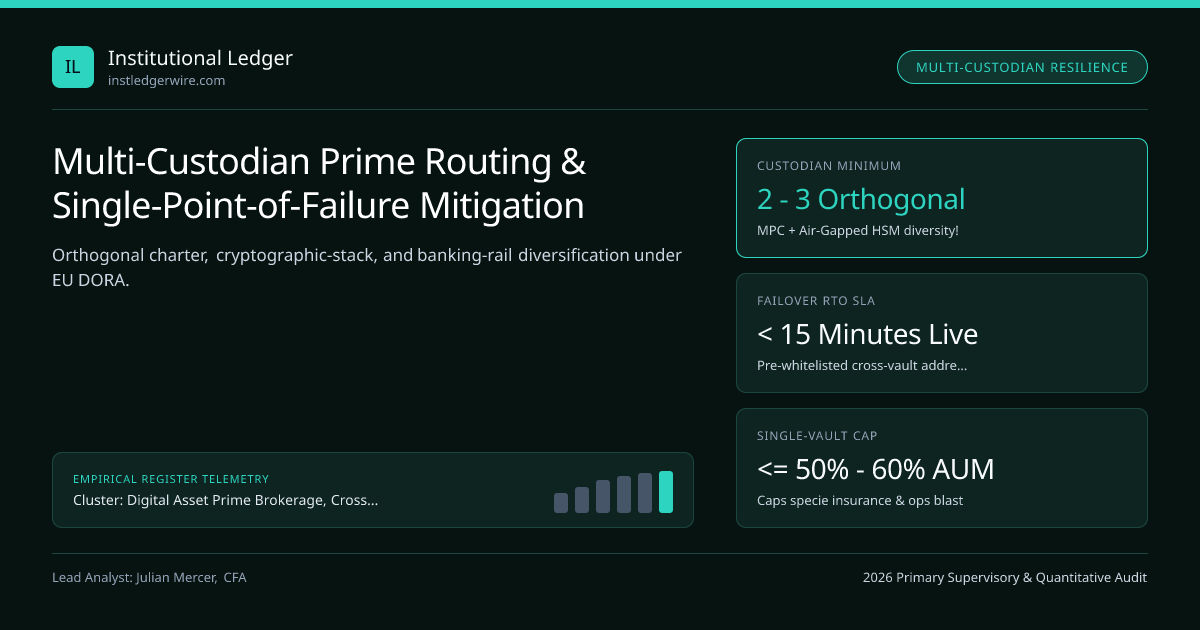
Multi-Custodian Prime Routing & Single-Point-of-Failure Mitigation
March 2023 proved that even billionaire treasuries can get locked out over a single weekend when relying on one banking or custody rail; institutional allocators mandate 2-to-3 orthogonal custodians wired into unified prime routing!
Stressed VaR & Concentration Liquidity Add-Ons for Altcoin Collateral
Accepting $40M of a token that trades only $12M per day at a flat 25% haircut guarantees lender insolvency; institutional prime risk engines enforce square-root ADV liquidity add-ons and hard 2%-depth caps!